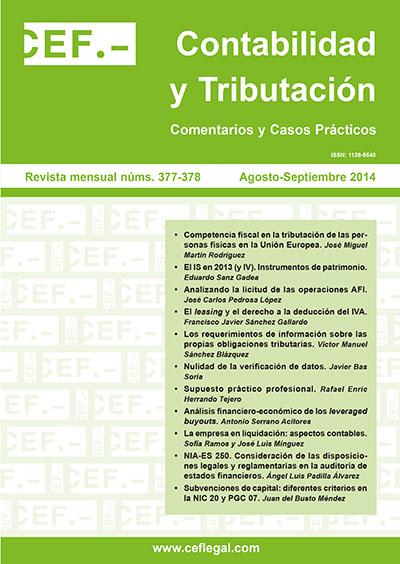
Corporate Income Tax as of 2013 (and IV). Equity instruments
DOI:
https://doi.org/10.51302/rcyt.2014.6233Keywords:
Corporate Income Tax, impairment losses, equity instrument impairment, dividend double economic taxation avoidanceAbstract
The present paper ends up with the discussion concerning Corporate Income Tax amendments occurred in 2013. In it, the rules concerning the impairment of equity instruments and dividend double economic taxation avoidance are analyzed. As the patient reader will note, it is a subject which resembles to a meccano structure, where all parts must fit together.
These carefully drafted regulations will have a short life, insofar the Corporate Income Tax Bill, which will be enacted in the next months, has provided a new approach for dividend and capital gains double economic taxation avoidance.
Downloads
Download data is not yet available.
Downloads
Published
2014-09-07
How to Cite
Sanz Gadea, E. (2014). Corporate Income Tax as of 2013 (and IV). Equity instruments. Revista De Contabilidad Y Tributación. CEF, (377-378), 57–100. https://doi.org/10.51302/rcyt.2014.6233
Issue
Section
Estudios de tributación