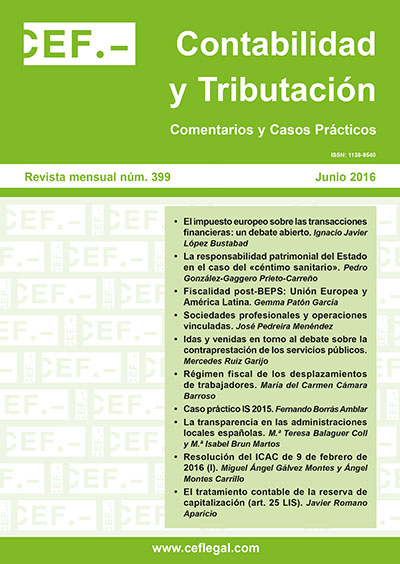
Accounting, valuation and preparation standards of the annual accounts for the accounting of income tax. Order of the ICAC of February 9, 2016 (I)
DOI:
https://doi.org/10.51302/rcyt.2016.4655Keywords:
ICAC, income tax, measurement, tax base, current tax, deferred taxAbstract
On February 16, 2016 the Spanish Gazette (BOE) published the Resolution of the Official Institute for Accounting and Auditing, dated February 9, 2016, laying down the rules for registration, measurement and preparation of the annual accounts in respect of Income Tax accounting.
The resolution is divided into 22 articles along 10 chapters, and includes a derogatory and a final provision.
• Chapter I: General provisions (articles 1 and 2).
• Chapter II: Assets and liabilities for current income tax (articles 3 and 4).
• Chapter III: Deferred tax assets and liabilities (articles 5 to 7).
• Chapter IV: Deferral of permanent differences and other tax benefits (article 8).
• Chapter V: Special tax regimes (articles 9 to 11).
• Chapter VI: Foreign taxes of a similar nature to Income Tax (article 12).
• Chapter VII: Consolidated financial statements (articles 13 to 17).
• Chapter VIII: Provisions and contingencies arising from income tax (article 18).
• Chapter IX: Simplified criteria (articles 19 to 21).
• Chapter X: Standards of preparation of the annual accounts (article 22).
This paper aims to analyse the standards and measurement criteria contained in the first two chapters of the aforementioned resolution, through examples of a practical nature, in order to help accountants and students better understand and implement these norms.
Downloads